


Welcome to AI Health Uncut, a brutally honest newsletter on AI, innovation, and the state of the healthcare market. If you’d like to sign up to receive issues over email, you can do so here.
Once again, it’s time for some seriously spicy healthtech news from September on the Digital Health Inside Out podcast, the Digital Health Vitals edition. 🌶️🔥
But first, I’m excited to be attending HLTH USA 2026, the marquee healthcare innovation event, Nov. 15-18 in Las Vegas! Join me: https://app.ingo.me/q/56jqv
On Monday, Sep 28, Alex Koshykov and I recorded the September Digital Health Vitals with special guest Patrick E. Donohue, founder of Hill Capital Corporation, a former healthcare analyst and banker whose next fund is all health tech. Stephanie Davis had to skip this one.
And here is August’s recap.
TL;DR
Oura postponed its $2.1B IPO on Tuesday, a day after we recorded. I called the 4x book weak on air.
ChatGPT inside Epic is a distribution event, not a technology event.
CommonSpirit paid $1.9B to leave Conifer, an RCM company. Patrick and I expect more insourcing.
Who owns the clinician AI layer in 5 years? I said Epic. Patrick said foundation models.
Thumbs: Heidi 3 up (mine with an asterisk), Tandem 2 up, Archy 3 up, Rightway split 3 ways.
Here is the episode outline:
1. Oura: Recorded Monday, Postponed Tuesday
2. ChatGPT + Epic: Distribution, Not Technology
3. The 5-Year Bet: Epic or the Foundation Models
4. CommonSpirit Paid $1.9B to Get Rid of RCM
5. Thumbs 👍🏼, Thumbs 👎🏼: Heidi, Tandem, Archy, Rightway
1. Oura: Recorded Monday, Postponed Tuesday
Alex’s setup: $2.1B, a book reportedly only 4x covered. The next morning Oura postponed, and I published Oura Is Peloton 2.0, and Not in a Good Way: 3 VCs selling 73% of the shares, $6.2M left for Oura after RSU taxes, and a 4x book against a 20x median. So much for lock-ups making the VC pump and dump impossible.
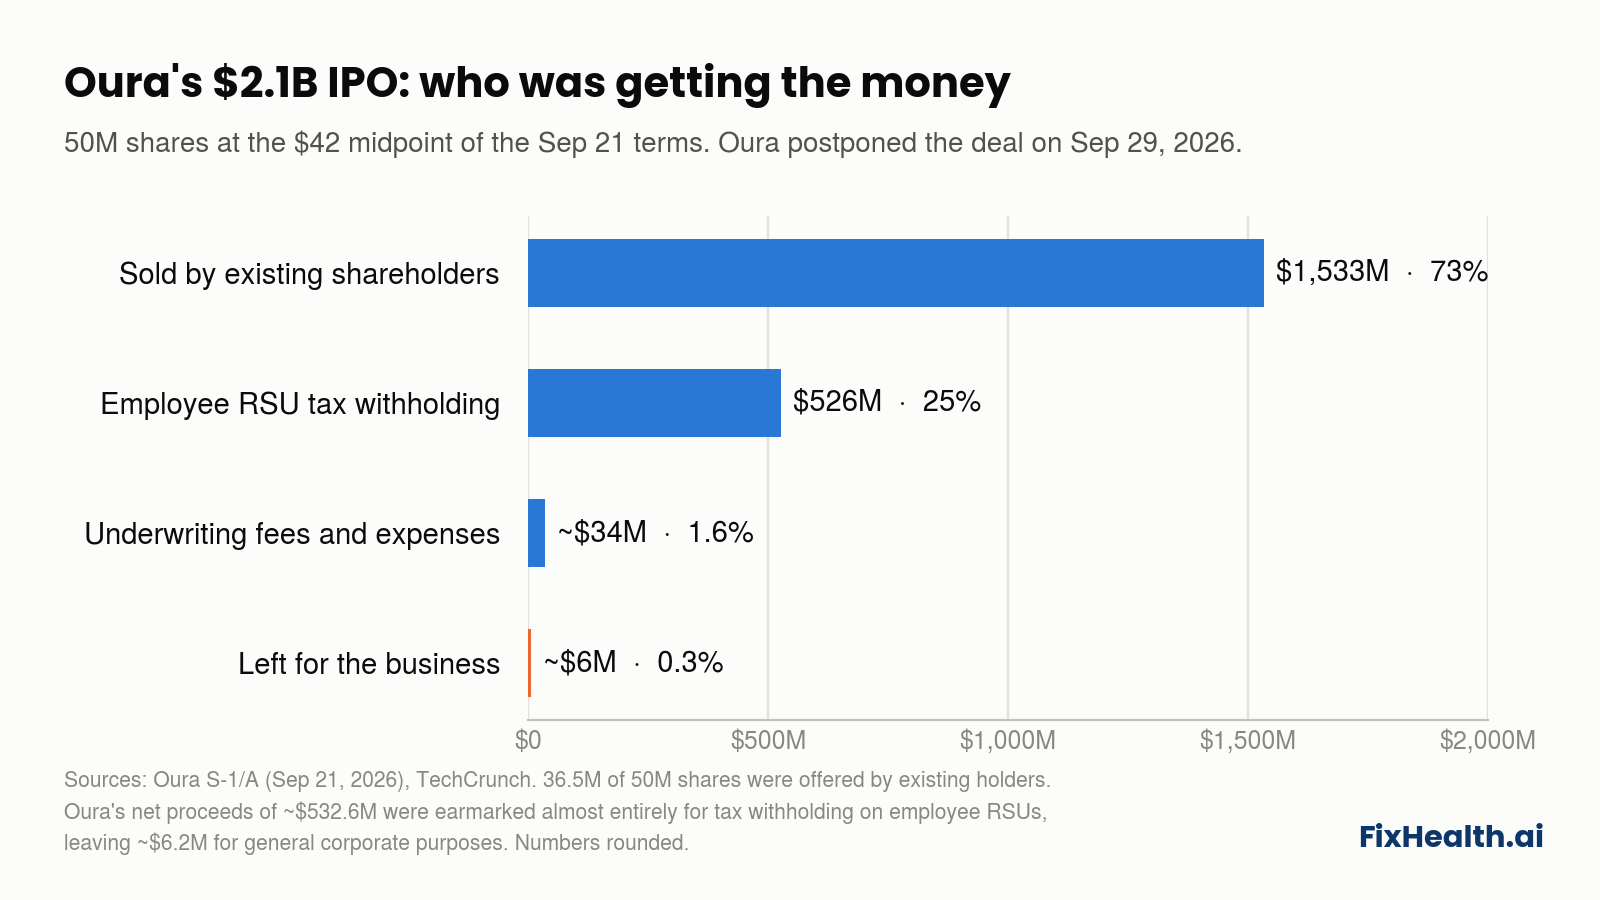
Patrick: “It is eye-opening to see the majority of the proceeds going to selling shareholders.” Verdict: great private company, hard public company. “If only Oura can tell me I’m about to have an asthma attack, that’s worth a lot of money.” That product is in CEO Tom Hale’s keynote, not the S-1.
My Peloton analogy: same 19.8% subscription share, same platform pitch, growth that stalls once enthusiasts have bought, as with Teladoc, Amwell and Cue Health.
Alex’s analogy was Fitbit 2015, and he’s right: Fitbit popped 48% on day one and sold to Google at 63% below its IPO price.
Wellness without the ring? Patrick: “A great company and a good investment can be two very different things.” His picks: National Beverage, Planet Fitness, Life Time. Mine: whoever the payer market pays, since there is no money in prevention. Alex: “Let’s all invest in our own health.”
2. ChatGPT + Epic: Distribution, Not Technology
I got plenty of grief for calling it the end of the healthtech AI industry. Alex: “You use your stories as clickbait.” 😉
The largest consumer AI product on the largest EHR, read-only because liability still belongs to the doctor. If “we integrate with Epic” is your moat, OpenAI’s relationship with Epic beats yours.
Patrick: a wrapper is valid only with a deep vertical edge. In EHR, “I would be very concerned.” His analogy: Target built its e-commerce on Amazon, then had to leave. Amazon won. Target survived.
Patrick’s filter: founders who design the human in the loop on purpose. My pushback: Hippocratic AI still has nurses babysitting AI conversations. Patrick: which 1%, 5% or 10% of the process needs a human?
OpenEvidence’s founders are reportedly fielding acquisition interest. My sources say Daniel Nadler has wanted to sell almost from day one, and the Anthropic announcement is packaging for a buyer. The moat was never the technology, the Llama derivative or the 100% accuracy claims. The moat is the 40% of US physicians using it.
3. The 5-Year Bet: Epic or the Foundation Models
Me: Epic, the easy bet. At UGM they covered everything, down to 10-clinician practices. Only antitrust would change that, and I actually hope it does.
Patrick: foundation models. “This is Netflix coming in during the era of Blockbuster.”
Alex: “It’s healthcare. It might be 20 years.” Not wrong. 😉
One agreement: frontier models beat fine-tuned wrappers, as I wrote in August 2024 and when fine-tuning died. My bet: they partner with Epic rather than replace it.
4. CommonSpirit Paid $1.9B to Leave Conifer
CommonSpirit pays ~$1.9B over 3 years to exit Conifer 6 years early. Conifer lays off 1,037 in November.
After 14 years with a specialist, CommonSpirit’s cost to collect was double the industry average. Paying $1.9B was cheaper than staying. 🤯
Everyone else is buying RCM: R1 at $8.9B, Ensemble at $12B, Commure at $7B, and Waystar exploring a sale after buying Olive AI’s remains. Somebody’s math is wrong.
Patrick expects more: “The ROI calc has literally changed dramatically in the last 6 to 12 months. Now Claude and GPT are just doing the models outright.” My caveat: real AI adoption in healthcare is 10%, and “autonomous” coding often means Bangalore.
5. Thumbs 👍🏼, Thumbs 👎🏼: Heidi, Tandem, Archy, Rightway
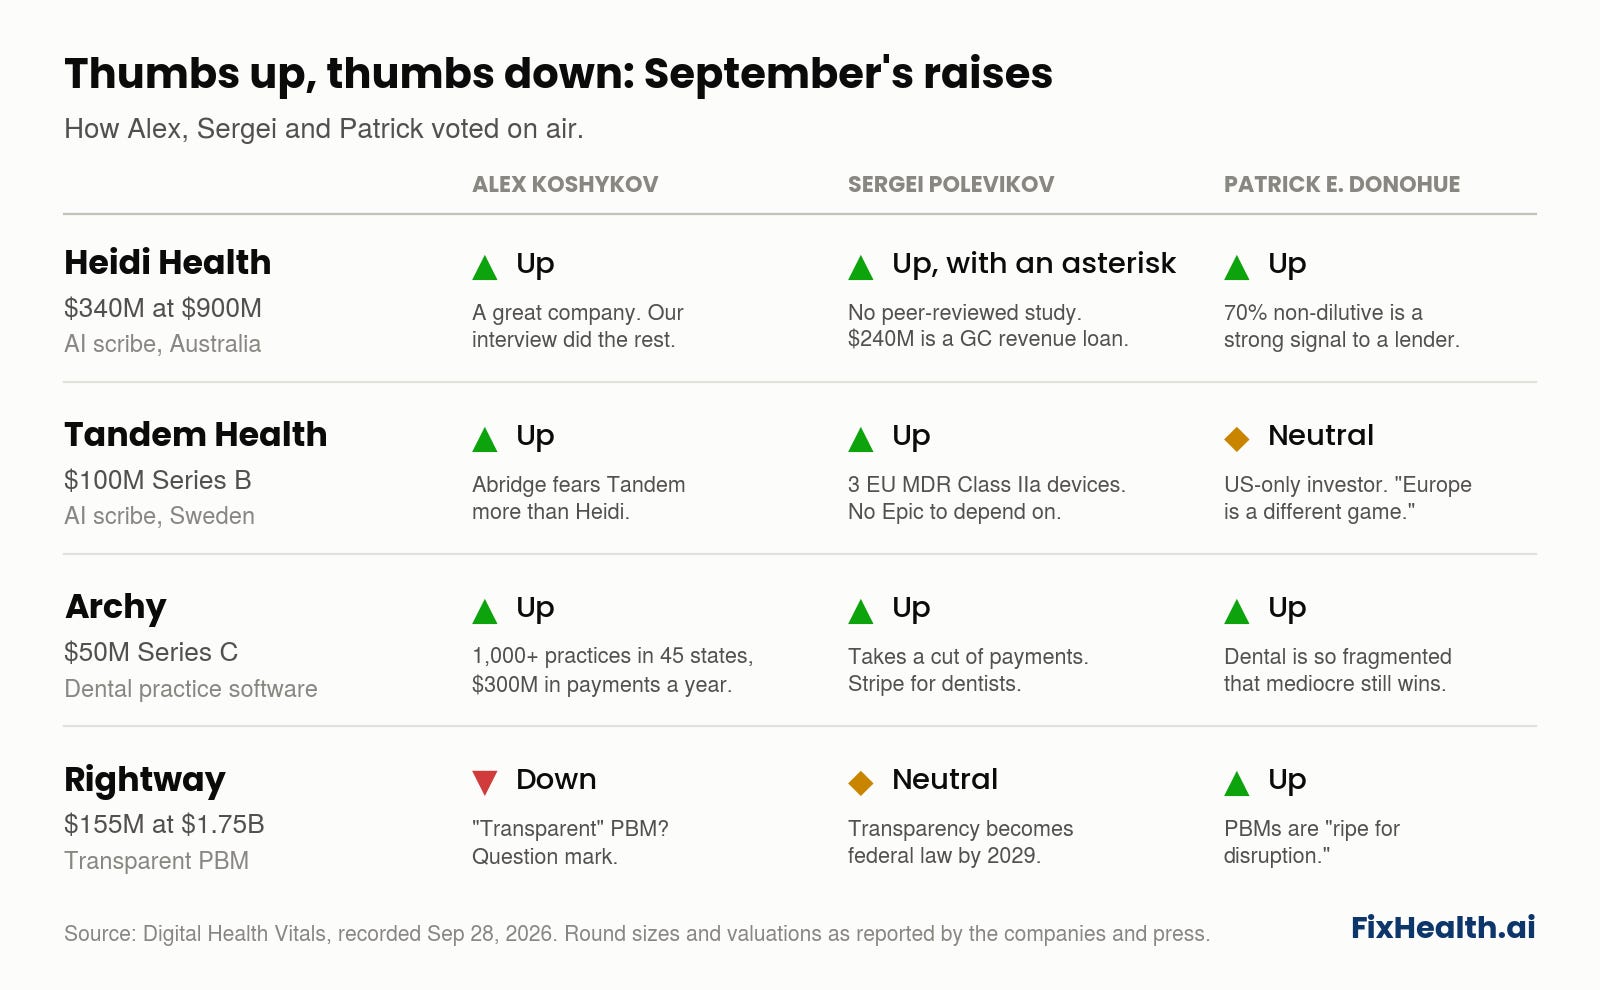
Heidi, $340M at $900M. My asterisk: still no peer-reviewed study, and $240M of it is General Catalyst lending against revenue. Patrick pushed back: founders protecting equity, and 70% non-dilutive means the lender trusts the revenue. “Stuff I see all the time that never hits the headlines.” Heidi stays a strong maybe.
Tandem Health, $100M Series B. Me: up. 3 EU MDR Class IIa devices, no Epic to depend on. Abridge should be frightened: it is not FDA cleared. Alex’s counter, via Nabla’s Alexandre LeBrun: once cleared, every release needs FDA sign-off, and scribes ship every 3 days. Patrick: neutral, a U.S.-only investor.
Archy, $50M Series C. All up. Dental is fragmented, and Archy takes a cut of $300M in payments. Me: It’s Stripe for dentists.
Rightway, $155M at $1.75B. Patrick: up, PBMs are “ripe for disruption.” Alex: down. Me: neutral, though the PBM revolt is overdue. Its moat is transparency, and the Consolidated Appropriations Act makes 100% rebate pass-through law for employer plans by 2029. When transparency is the legal minimum, what’s left of that moat? 🤷🏼♂️
Catch the full episode here:
👉🏼 And don’t forget to subscribe. 😉
Upcoming events: Patrick’s Hill Capital Summit is Nov 12 in St. Paul. Alex and I are recording at HLTH, Nov 15 to 18 in Las Vegas. See you there. Daniel Nadler, the invitation stands. 😉
Like what you’re reading in this newsletter? Want more in-depth investigations and research? Alright then, go tell your friends!
👉👉👉👉👉 Hi! My name is Sergei Polevikov. I’m an AI researcher and a healthcare AI startup founder. In my newsletter ‘AI Health Uncut,’ I combine my knowledge of AI models with my unique skills in analyzing the financial health of digital health companies. Why “Uncut”? Because I never sugarcoat or filter the hard truth. I don’t play games, I don’t work for anyone, and therefore, with your support, I produce the most original, the most unbiased, the most unapologetic research in AI, innovation, and healthcare. Thank you for your support of my work. You’re part of a vibrant community of healthcare AI enthusiasts! Your engagement matters. 🙏🙏🙏🙏🙏